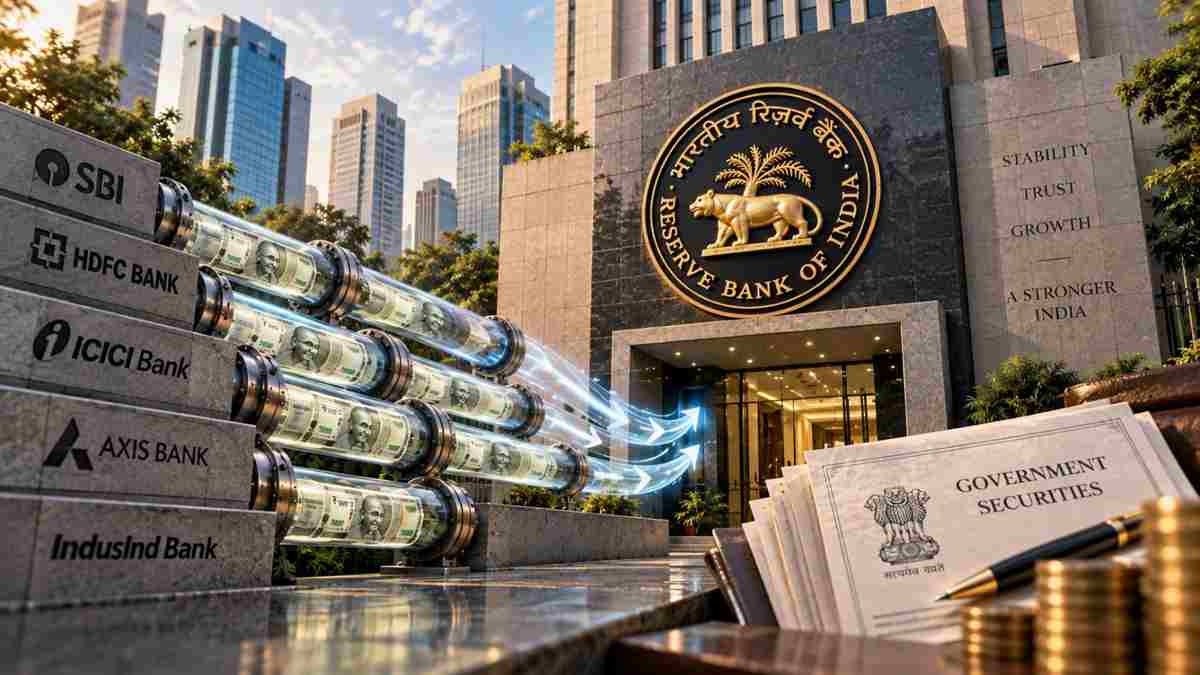
MUMBAI – The Reserve Bank of India is set to remove ₹1 lakh crore from the banking system as surplus liquidity has climbed above ₹10 lakh crore and overnight rates have fallen below the RBI’s policy rate.
The RBI will sell government securities through three open market operations this month. It will sell ₹50,000 crore on September 17, followed by ₹25,000 crore each on September 21 and September 28.
The move follows weak demand for some of the RBI’s earlier liquidity-absorption operations. The central bank had used variable-rate reverse repo auctions to take excess funds out of banks, but longer-duration operations attracted much less money than the RBI had offered.
Banking-system liquidity was in a ₹10.43 lakh crore surplus on September 10, according to RBI data. Core liquidity was estimated at around ₹13–14 lakh crore. A large part of the recent increase came from foreign-currency inflows. Banks raised about $127.23 billion through FCNR(B) deposits, while total inflows under the special foreign-currency mobilisation programme reached about $136.38 billion.
The money came into India as foreign currency, but the RBI’s intervention also added rupee liquidity to the domestic financial system. Banks were left with a large pool of funds that could be lent or parked in short-term markets.
The effect is visible in overnight borrowing rates. The weighted average call rate was 5.02%, below the RBI’s 5.25% repo rate. That gap is important. The repo rate is the RBI’s main policy signal, while the call rate reflects the cost at which banks borrow from each other overnight. Too much cash can push the market rate below the policy rate and weaken the transmission of RBI decisions.
The response to the VRRR operations also explains the shift towards bond sales. Banks parked only ₹60,449 crore against a ₹5 lakh crore offer in one 26-day operation. A separate four-day operation attracted around ₹3.44 lakh crore.
OMO sales work differently. When banks and investors buy government securities from the RBI, money moves out of the banking system and into those securities. The liquidity withdrawal is therefore more durable. Government bond yields have already moved higher. The 10-year benchmark yield reached 7.01%, its highest level since June 3, while the five-year yield rose to 6.59%.
There is another pressure building at the same time. India’s August retail inflation rose to 4.82% from 4.45% in July, while core inflation reached around 4.2%. Brent crude has also moved above $100 a barrel, with prices approaching $108 during the recent surge.
Higher oil prices can raise costs for transport, manufacturing and other businesses, while higher bond yields can increase the cost of borrowing for companies and the government. The RBI is therefore trying to bring excess liquidity under control while inflation and crude prices are moving in the opposite direction. The banking system has more than ₹10 lakh crore in surplus liquidity, the call rate is 23 basis points below the 5.25% repo rate, and the 10-year government bond yield has crossed 7%.
The ₹1 lakh crore OMO programme puts those three numbers at the centre of India’s monetary-policy debate.