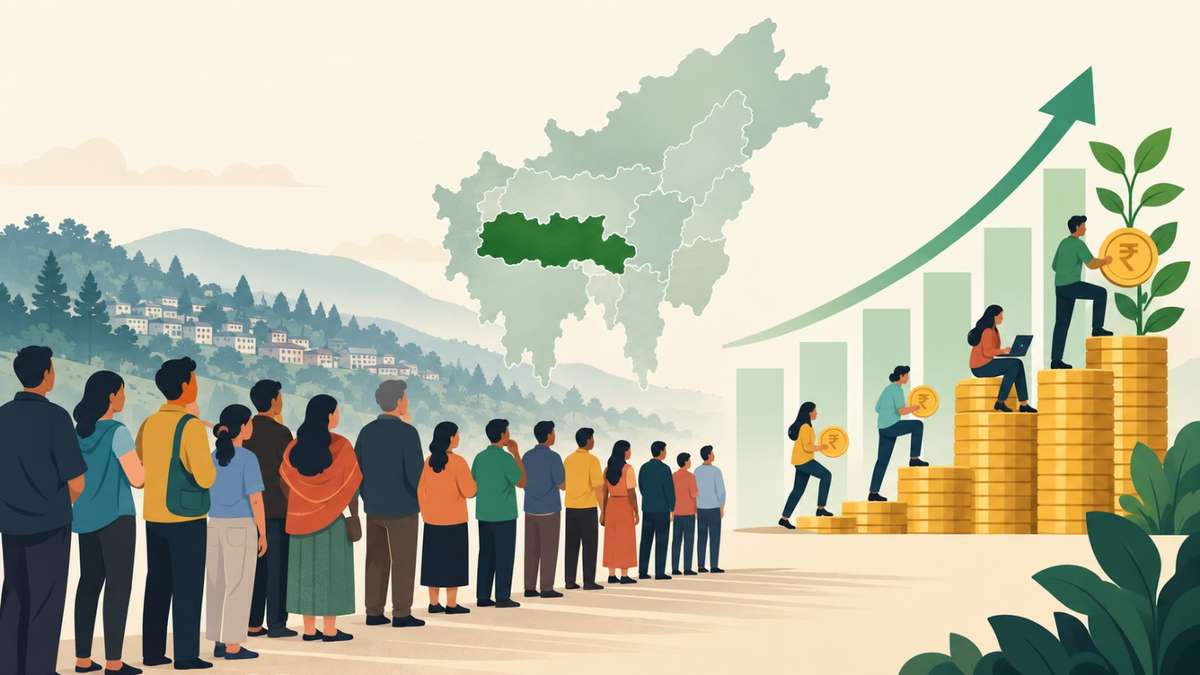
Meghalaya holds ₹5,490 crore in mutual-fund assets. Only 4.2% of its households participate in securities markets. The SEBI Investor Survey 2025 found that just 4.2% of households in the state held securities-market products, against a national average of 9.5%. The survey’s definition is broader than mutual funds alone. It covers mutual funds, ETFs, stocks and shares, futures and options, REITs and InvITs, corporate bonds and alternative investment funds. A sizeable pool of professionally managed money can therefore exist without a large share of households taking part directly.
Among the northeastern states the participation ranking runs in a different order from absolute AUM. Sikkim recorded 10.1% household penetration, Arunachal Pradesh 7.9%, Assam 6.5%, Mizoram 6.3%, Tripura 5.3%, Meghalaya 4.2% and Nagaland 3.4%. Sikkim again sits at the top. Nagaland sits at the bottom.
Nationally the survey found that 63% of Indian households were aware of at least one securities-market product, yet only 9.5% participated. Fieldwork covered more than 90,000 households across more than 400 towns and over 1,000 villages. The urban-rural divide is sharp: 15% of urban households participated against 6% of rural households. Larger urban centres showed higher penetration than smaller settlements.
The barriers are practical rather than abstract. Among non-investing households, 74% cited complexity and information gaps, 73% cited risk and return concerns, and 51% pointed to trust and transparency issues. For mutual funds and ETFs specifically, 27% said they lacked knowledge about how the products work and another 27% said they did not know how to begin. When asked what would encourage them, 73% of non-investors pointed to easier processes and access, 62% to education and information, 61% to cost efficiency and 58% to trust and assurance. Only 15% cited improved economic conditions or a positive market outlook.
The information channel has shifted. Social media was the leading source of securities-market awareness among non-investors, cited by 56% nationally. Television remained significant at 40%. For mutual funds and ETFs the social-media figure rose to 57%.
The Northeast numbers therefore refuse a simple reading. Meghalaya does not have the highest per-capita mutual-fund exposure in the region, nor the lowest. It ranks high on absolute AUM, relatively high on AUM per capita and highest on AUM as a share of state GDP, while remaining near the bottom on broad household participation.
Sikkim combines the highest per-capita AUM of ₹39,051 with the highest participation rate of 10.1%, above the national average. Nagaland combines modest AUM figures with the lowest participation rate of 3.4%.
Three measurements are at work: the volume of money already inside mutual funds, the share of households that participate in securities markets, and the concentration of those assets. They do not move together.
For Meghalaya the contrast is especially sharp. The state holds ₹5,490 crore in average mutual-fund AUM, ₹16,394 in AUM per capita and assets equivalent to 17% of SGDP, while only 4.2% of households take part in the wider securities market.
The data does not show indifference. It shows uneven distribution. A substantial pool of financial assets can coexist with limited household participation.